Youth Protests Prompt PM Modi’s Warning to Corporate-sector
The Corporate Tax Windfall and the Missing Trickle-Down in India
Why India’s Corporate Tax Breaks Failed to Reach Workers
Corporate Coffers Overflow with Surplus Capital
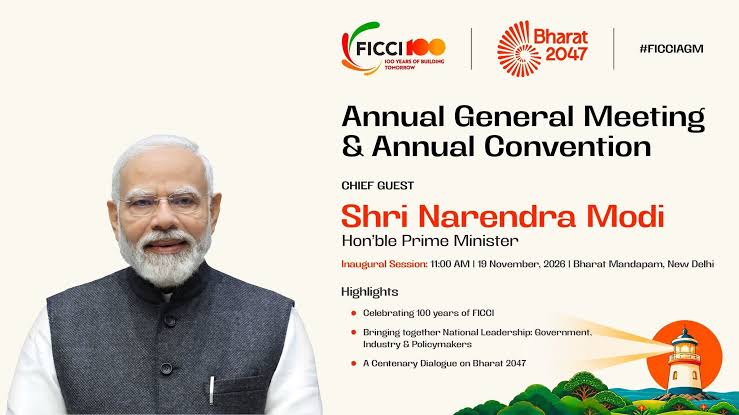
Prime Minister Narendra Modi’s pointed rebuke to corporate leaders at the FICCI annual general meeting in November 2026—accusing India Inc. of pocketing corporate tax cuts and Rs 12 lakh income-tax relief without raising salaries or expanding hiring—signals a strategic political shift ahead of the 2027 Union Budget. By publicly calling out industry’s passive “Modi ji, you do it” attitude, the government is shifting blame for stagnant household consumption onto private boardrooms while warning executives not to expect fresh tax concessions. Simultaneously, this rare public chiding reflects mounting political pressure from the streets.
Following the Gen Z-led Cockroach Janta Party (CJP) protests over exam leaks, unemployment, and voter roll revisions, New Delhi has been forced onto the defensive. Rather than commissioning an independent study into youth frustration, the central government has largely responded with tactical policy concessions—such as setting up an NTA reform taskforce—while dismissing broader CJP agitations as politically co-opted unrest.
Record Profits, Stagnant Pay
In September 2019, the Indian government introduced one of the most sweeping corporate tax reforms in the country’s history. The base corporate tax rate for domestic companies was slashed from 30% to 22% (an effective rate of roughly 25.17% including surcharge and cess) for firms willing to forego special exemptions, while new manufacturing companies incorporated after October 2019 were offered an even lower base rate of 15%. Alongside this, the Minimum Alternate Tax (MAT) was reduced from 18.5% to 15%. The policy rationale was anchored in classic supply-side economics lowering the tax burden would leave corporations with substantial surplus capital, which they would then channel into fresh capital expenditure (capex), job creation, higher employee wages, and better returns for stakeholders. Seven years on, macroeconomic data, parliamentary reviews, and official government surveys indicate that while corporate balance sheets have strengthened dramatically, the expected transmission of these gains to workers and everyday stakeholders has largely stalled.
The Volume of Tax Relief and Corporate Benefits
The scale of fiscal relief extended to Indian industries, business houses, real estate developers, and private financial institutions has been massive. According to Finance Ministry estimates and Parliamentary Standing Committee assessments, the 2019 corporate tax cut alone resulted in immediate revenue foregone of approximately Rs 1.45 lakh crore in its first year, with cumulative revenue losses crossing Rs 1.84 lakh crore over the first two fiscal years (FY20 and FY21). Beyond rate cuts, annual Union Budget statements on “Revenue Impact of Tax Incentives” show that corporations continue to claim roughly Rs 75,000 crore to over Rs1 lakh crore annually through accelerated depreciation, Special Economic Zone (SEZ) deductions, infrastructure incentives, and sector-specific exemptions.
Lower Effective Tax Rates
For businesses, real estate firms, and private banks, these measures delivered three distinct advantages. Large corporations saw their effective tax outgo drop from roughly 27–28% prior to 2019 down to an average of 21–22%, directly boosting net profit margins. Balance Sheet De-leveraging: Private financial institutions and capital-intensive conglomerates used tax savings to retire high-cost debt and strengthen liquidity buffers rather than funding risky greenfield expansions. Lower tax liabilities boosted post-tax earnings per share (EPS), driving a sustained surge in stock market valuations and shareholder wealth.
Reliance Industries and the Adani Group: Scale of Relief
Following the 2019 tax overhaul and by utilising existing capital allowances and SEZ benefits across its refining and digital verticals, RIL’s standalone effective tax rate dropped significantly below the old 30% statutory benchmark—hovering around 16.5% to 17% in key post-cut fiscals (such as FY22, where it paid Rs7,702 crore in tax on massive pre-tax profits). Across its consolidated operations, retaining tens of thousands of crores in post-tax cash flows helped RIL become net-debt free ahead of schedule and fund its massive retail and telecom expansion.
Adani Group
Operating primarily in capital-intensive infrastructure—ports, power, renewable energy, airports, and SEZs—Adani portfolio companies have historically relied less on the 22% no-exemption regime and more on accelerated depreciation, infrastructure-linked deductions under Section 80-IA, and SEZ tax holidays under Section 10AA. Consequently, flagship entities such as Adani Enterprises paid relatively modest direct corporate income taxes relative to their market capitalisation (for example, around $58.3 million or ~Rs 440 crore in FY22). In its FY25 Tax Transparency Report, the Adani Group reported total global tax and exchequer contributions of Rs74,945 crore, though the vast majority of this comprises indirect taxes (GST, customs duties) collected from consumers and royalties rather than direct corporate profit tax. Earlier Comptroller and Auditor General (CAG) audits had also flagged specific tax exemptions worth hundreds of crores (such as Rs234 crore in a single assessment review) granted to group entities under SEZ provisions.
Have Companies Transferred Benefits to Workers and Stakeholders?
Empirical evidence overwhelmingly confirms that the private sector has not proportionately shared this tax windfall with its workforce. By 2025–26, profits of Nifty 500 companies surged to an all-time high of 5.2% of India’s GDP, growing nearly three times faster than the broader economy. Yet, worker compensation moved in the opposite direction. Stagnant Real Wages: Data from the Economic Survey (2024–25 and 2025–26) and the Annual Survey of Industries (ASI) reveal that while nominal wages for organised factory workers grew by roughly 5.3% in 2024–25, inflation-adjusted (real) wage growth stood at a negligible 0.7% (and was negative in 2022–23). Between 2017–18 and 2023–24, real monthly earnings for regular salaried workers actually declined.
Widening Internal Pay Gaps-Policy Pushback
While ordinary factory workers averaged Rs2.28 lakh annually in 2024–25, managerial and supervisory pay rose to 6.36 times that of shop-floor workers. Furthermore, corporate profit growth of 22% to 26% in recent quarters has coincided with single-digit salary increments and sluggish formal job creation.The disconnect became so stark that by November 2026, the Union government and Prime Minister publicly questioned India Inc. for hoarding tax concessions and ease-of-doing-business gains without raising employee salaries or expanding hiring. Ultimately, while tax cuts and exemptions successfully fortified corporate balance sheets and rewarded equity shareholders, companies chose to retain surpluses as cash reserves, reduce debt, or automate operations rather than raise wages. Without broad-based wage growth, domestic consumer demand has remained subdued—proving that tax relief for corporations does not automatically translate into shared prosperity for workers
Editor, Prime Post
Ravindra Seshu Amaravadi, is a senior journalist with 38 years of experience in Telugu, English news papers and electronic media. He worked in Udayam as a sub-editor and reporter. Later, he was associated with Andhra Pradesh Times, Gemini news, Deccan Chronicle, HMTV and The Hans India. Earlier, he was involved in the research work of All India Kisan Sabha on suicides of cotton farmers. In Deccan Chronicle, he exposed the problems of subabul and chilli farmers and malpractices that took place in various government departments.
Email: ravindraseshu7@gmail.com
Mobile: 9063718675
Modi transforming into Robinhood. Too late, but needed.
Enough was given to corporates but not shared back.
Also he has to think to reduce IT for salaried employees.
Every product has GST & some include cess too over and above IT brackets.
It’s better to calculate the way it’s calculated for corporates. Gross profit minus expenses, taxable income.
The same way it should be calculated for Salaried Professionals, total tax minus indirect taxes paid should be the balance tax to be paid. It will help to reduce cash transactions and ensure transparency.
Or on avg 10% tax rebate should be given for the salaried and IT returnees.